End of the Annual Vetting: FCA and Bank of England Want to Scrap City's 139,000-Staff Certification Regime
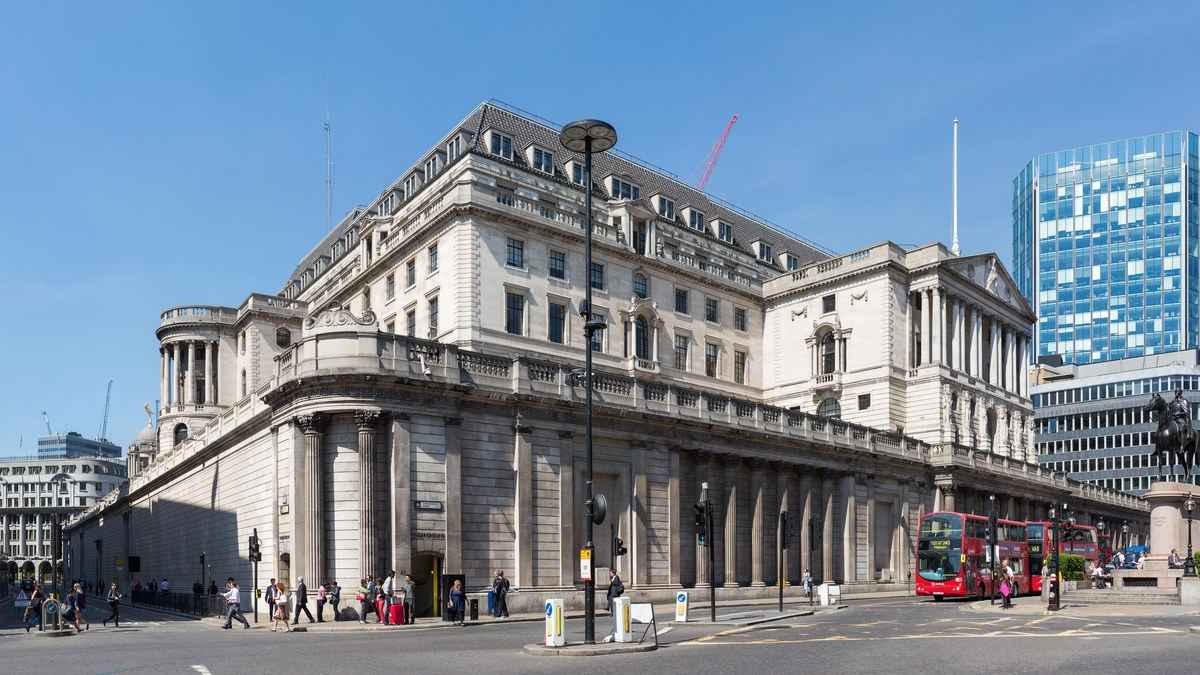
Photo: Diliff, via Wikimedia Commons (CC BY-SA 3.0)
The most resented rule in British banking is finally being trimmed. On Thursday, the Financial Conduct Authority and the Bank of England's Prudential Regulation Authority proposed tearing up the annual vetting of roughly 139,000 finance staff — the Senior Managers and Certification Regime brought in a decade ago after the 2008 crash to make bankers personally accountable for what their firms did.
The message from the watchdogs is blunt: the paperwork outgrew the protection. The Bank of England reckons the changes will save firms around £2 billion over ten years — and the FCA's own numbers say annual compliance costs would fall by more than half, to about £230 million.
What actually changes for City staff
The biggest single cut is the Certification Regime itself. Right now, some 139,000 people below senior-manager level have to be re-certified as fit and proper every single year and appear on the Financial Services Register — a public online directory that also gets scrapped under the plan. That whole annual ritual goes.
For senior hires, the regulators want to replace pre-approval with notification for a swathe of roles — chief actuaries, risk and audit chairs among them. The firm tells the regulator who it appointed; the regulator does not sign them off in advance. The line is drawn where it matters most: chief executives, finance chiefs and chairs still need regulatory approval before they start, and the regulators can still demand pre-approval for otherwise "notified" roles in high-risk cases. Firms remain responsible for making sure their people are competent and behave — the same accountability, fewer forms.
The threshold nobody talked about
There is a quieter change with real bite. The proposals raise the threshold for reporting conduct-rule breaches for most staff below senior-manager level and streamline Conduct Rule training. As The Times reports, firms will no longer have to report first written warnings in most roles — the regulators' argument being that chasing every minor breach drowned the serious ones.
Enjoyed this guide?
Britain Daily is an independent publication. Every guide is researched, written and carefully edited, and kept free forever. If this saved you time or made your life easier, please don't let the effort go unnoticed — support our work with whatever you can, from $1 upward. Every dollar keeps the guides coming.
💛 Donate via PayPalThe quotes that matter
Katharine Braddick, the PRA's chief executive, used her first major speech in the role — at a Mansion House dinner on Thursday — to frame the overhaul as accountability kept where it counts. "The Senior Managers Regime is an essential part of the UK's regulatory framework," she said. "These proposals keep checks in place for the most important roles, meaning individuals are accountable for their actions, but reduce the administrative burden where it isn't needed, giving firms more time to invest in growth-focused activities and greater flexibility in onboarding senior talent."
Sarah Pritchard, the FCA's deputy chief executive, said the regime had delivered "significant improvements in accountability and governance" — but "we can achieve the same impact with a more streamlined regime, supporting our aim to be a smarter regulator."
Why now — and why it had to be phase two
The timing is no accident. This is phase two of a post-crisis rethink the government is driving as part of a broader red-tape bonfire meant to make the City more competitive — the same week the PRA's new boss unveiled a five-year strategy with competitiveness and growth baked into day-to-day supervision. Phase one already landed back in April, trimming senior-manager accountability rules.
Braddick was also keen to stress what is not being sacrificed. Resilience stays the PRA's "first priority", she said, with a new dedicated supervisory division for operational and cyber resilience and a markedly sharper focus on firms' ability to withstand attacks. Her warning covered "unprecedented volatility, concentration risks" and cross-border financial crime, with fast-emerging tech, as FCA boss Nikhil Rathi put it, "putting these on steroids."
The catch: Parliament has to say yes
Some of the reforms need primary legislation, which is why the FCA and PRA are consulting now — so they can move fast once the law passes. Final policy is expected in 2027.
After ten years of firms treating the annual certification round like a tax return, there is genuine relief in this. But the test will be the first scandal under the lighter regime. If accountability survives the paperwork diet, Braddick and Pritchard will look like reformers. If it doesn't, the pendulum will swing back harder than it did in 2008. The City is about to find out which.
Sources
- Reuters — UK financial regulators propose easing vetting rules for finance employees (22 October 2026)
- Bank of England — Regulators unveil plans to simplify Senior Manager and Certification Regime (22 October 2026)
- The Times — Regulator warns the City to get serious on cybersecurity, on SM&CR proposals (22 October 2026)
- Traders Union — UK regulators propose streamlining senior managers regime to cut firms' compliance costs (22 October 2026)
Enjoyed this guide?
Britain Daily is an independent publication. Every guide is researched, written and carefully edited, and kept free forever. If this saved you time or made your life easier, please don't let the effort go unnoticed — support our work with whatever you can, from $1 upward. Every dollar keeps the guides coming.
💛 Donate via PayPal